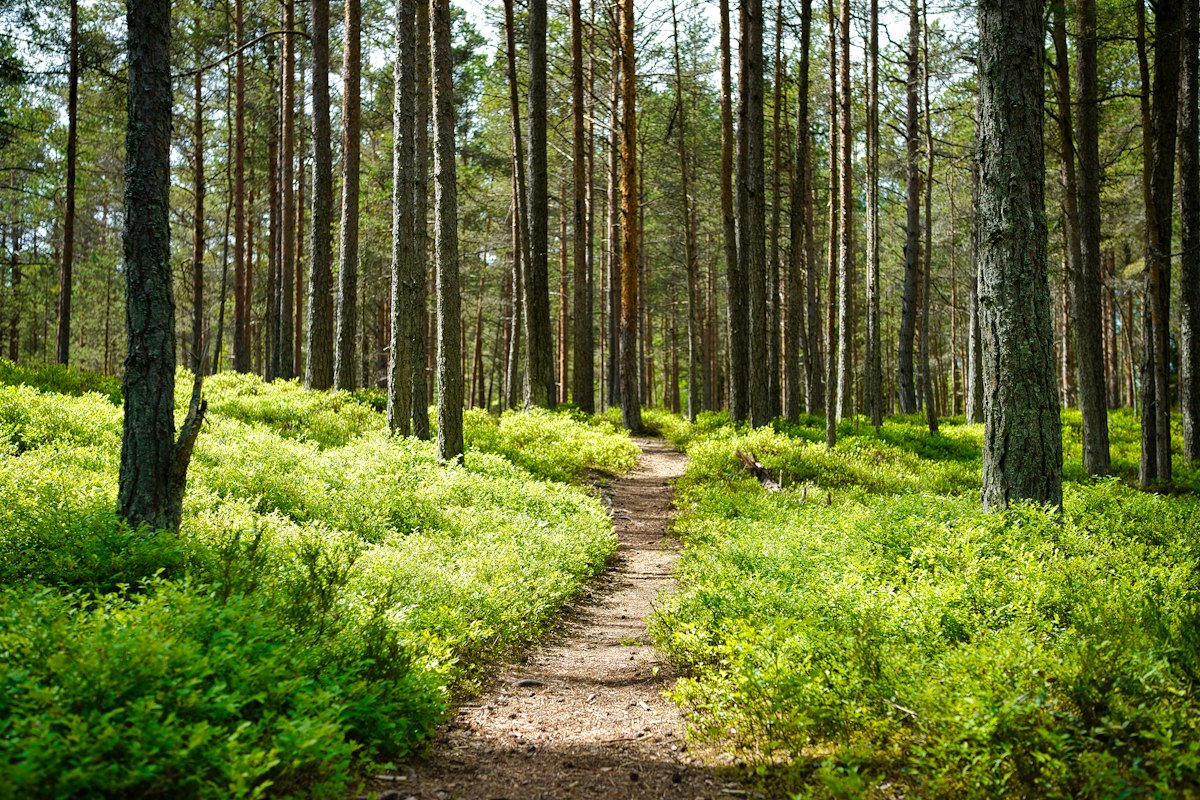
London Mayor Sadiq Khan's heat resilience plan says making the most vulnerable homes resilient would cost between £9 billion and £45 billion, against £1.5 billion in costs from the 2022 heatwaves, with private investment needed and insurers such as Swiss Re and Zurich framing heat as a risk that amplifies other losses.
London's mayor has put a price on preparing the capital's homes for extreme heat, and the figure is large. According to a Bloomberg report published by Insurance Journal on June 25, 2026, the city's heat resilience plan, which the article calls Heat Ready London, estimates that making the most vulnerable homes resilient would cost between £9 billion and £45 billion. By comparison, the heatwaves of 2022 cost London £1.5 billion, or about $2 billion. The wide range reflects uncertainty over how many homes and what measures are included, and the article does not explain how the two ends of the range were built. Other details sometimes quoted in coverage of the plan, such as particular alert levels or monthly record temperatures, are not in this source and are left out.
The numbers
The plan says private investment will be needed, since public funds alone are unlikely to cover a bill of that scale. About one million homes in London are at high risk of overheating, according to the report. Mayor Sadiq Khan said that the costs of inaction outweigh the cost of action. Simple arithmetic shows how the numbers compare: £9 billion is six times the £1.5 billion cost of the 2022 heatwaves, and £45 billion is thirty times, so the argument depends on heatwaves recurring and growing in severity over many years, which the article implies but does not quantify.
The heat itself
The report describes temperatures around 35C in London. Greenpeace recorded more than 55C on pavements and platforms, a figure that reflects surface heat in direct sun and not air temperature. London Ambulance Service logged 642 Category 1 calls on the Wednesday, the highest number it has ever recorded for a day. Category 1 is the most urgent category, for life-threatening conditions. The article does not report any heat deaths and does not say how many of the calls were related to heat. That is an important qualification: the call volume is consistent with heat stress, but the report does not establish the cause of each call.
What the plan proposes
The plan lists priorities including external shutters, shade, trees, access to swimming, cooler schools and air conditioning for vulnerable settings. These are a mix of passive measures, such as shade and shutters, which reduce indoor temperatures without using energy, and active cooling for places that care for vulnerable people. The emphasis on schools and vulnerable settings reflects the people most at risk, such as children, older residents and those with health conditions. The article does not give a breakdown of the cost by measure.
The insurance angle
The report links the plan to insurance. Swiss Re Institute calls heat a risk amplifier, meaning that heat does not only cause direct damage but also makes other risks worse, for example by stressing power grids, damaging infrastructure, harming health and raising the chances of fire. Linda Freiner of Zurich spoke about pricing resilience, which refers to the question of whether insurers can reflect the benefits of resilience measures in the prices they charge. If a building has shutters, shade and cooling, an insurer might regard it as a better risk, but the report does not describe any actual pricing scheme.
The report also notes that Switzerland is warming more than twice as fast as the global average and that French minister Éléonore Caroit said buildings were not designed for these temperatures. Those remarks put London's problem into a European context: much of the building stock in northern Europe was designed for cooler climates.
Who pays
The estimated bill raises the question of who pays for retrofitting homes. Many vulnerable homes are rented or owned by people with limited means, and the plan says private investment will be needed. The article does not describe any financing mechanism, so it is not clear whether the money would come from landlords, lenders, insurers or grants. Insurers and reinsurers have a role as investors and as risk assessors, but the report does not say they will fund the programme.
What to take from it
The plan's central claim is economic: spending on resilience now is cheaper than paying for the consequences of repeated heatwaves. The range of £9 billion to £45 billion shows how uncertain the cost is. For insurers, the message is that heat is a growing risk worth modelling. For homeowners and landlords, it is a signal that cooling and shading measures may become more valuable. For policymakers, it highlights the need for funding models.
Questions the report leaves open
Several questions cannot be answered from the article. It does not say how many homes make up the group of the most vulnerable, so the cost per home cannot be calculated. It does not state the time frame over which the £9 billion to £45 billion would be spent. It does not explain how the 2022 cost of £1.5 billion was calculated, for example whether it includes health costs, lost productivity or damage to property. And it does not say how much of the cost insurers could be expected to bear. These gaps matter because the argument that action is cheaper than inaction depends on the frequency of future heatwaves and on how long the measures last.
For insurers, the story is a reminder that heat is a risk that spreads through other lines of business, such as health, property, business interruption and infrastructure. For residents, the practical measures, shade, shutters and ventilation, are known and relatively simple; the challenge identified in the plan is scale and funding.
Limits
This article summarises a news report of the plan and not the plan itself, and it contains no data on health outcomes or costs per measure. It is general information, not insurance or planning advice.
Key Points
- 1The 2022 heatwaves cost London £1.5 billion ($2 billion), and making the most vulnerable homes resilient would cost £9 billion to £45 billion, with private investment needed.
- 2Mayor Sadiq Khan said the costs of inaction outweigh the cost of action, and about 1 million London homes are at high risk of overheating.
- 3Temperatures were around 35C, Greenpeace recorded more than 55C on pavements and platforms, and London Ambulance Service logged 642 Category 1 calls on a Wednesday, its highest ever; the article reports no heat deaths.
- 4The plan's priorities include external shutters, shade, trees, swimming access, cooler schools and air conditioning for vulnerable settings.
- 5Swiss Re Institute calls heat a risk amplifier, and Zurich's Linda Freiner spoke about pricing resilience, framing the issue as one for insurers as well as for city planners.
Why This Matters
Heat is usually less visible in insurance figures than floods or storms, but it affects health, infrastructure and property. A city estimating a bill in the tens of billions for housing alone shows why resilience financing, and insurers' view of it, is becoming part of climate planning.
Original Source
Insurance Journal, reporting Bloomberg (June 25, 2026) ↗Related Stories

High Court Holds a Roofer's 'Reasonable Precautions' Hot-Works Condition Is Absolute, Leaving Attleys Roofing Without Cover for a School Fire Against QBE
October 29, 2026
Moody's Keeps UK Life and Property Insurers at a Stable Outlook but Warns That Falling Prices Will Squeeze Underwriting Margins More Heavily in 2027
October 26, 2026
Moody's Holds France at Aa3 With a Negative Outlook, a Reprieve Conditioned on a 2027 Budget, After 10-Year Yields Hit 5.1%
October 24, 2026
Lloyd's of London's 2026 Half-Year Report: £3.5 Billion Profit, a 90.8% Combined Ratio and a Chief Executive Warning That Rates Are Past Their Peak
October 23, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer