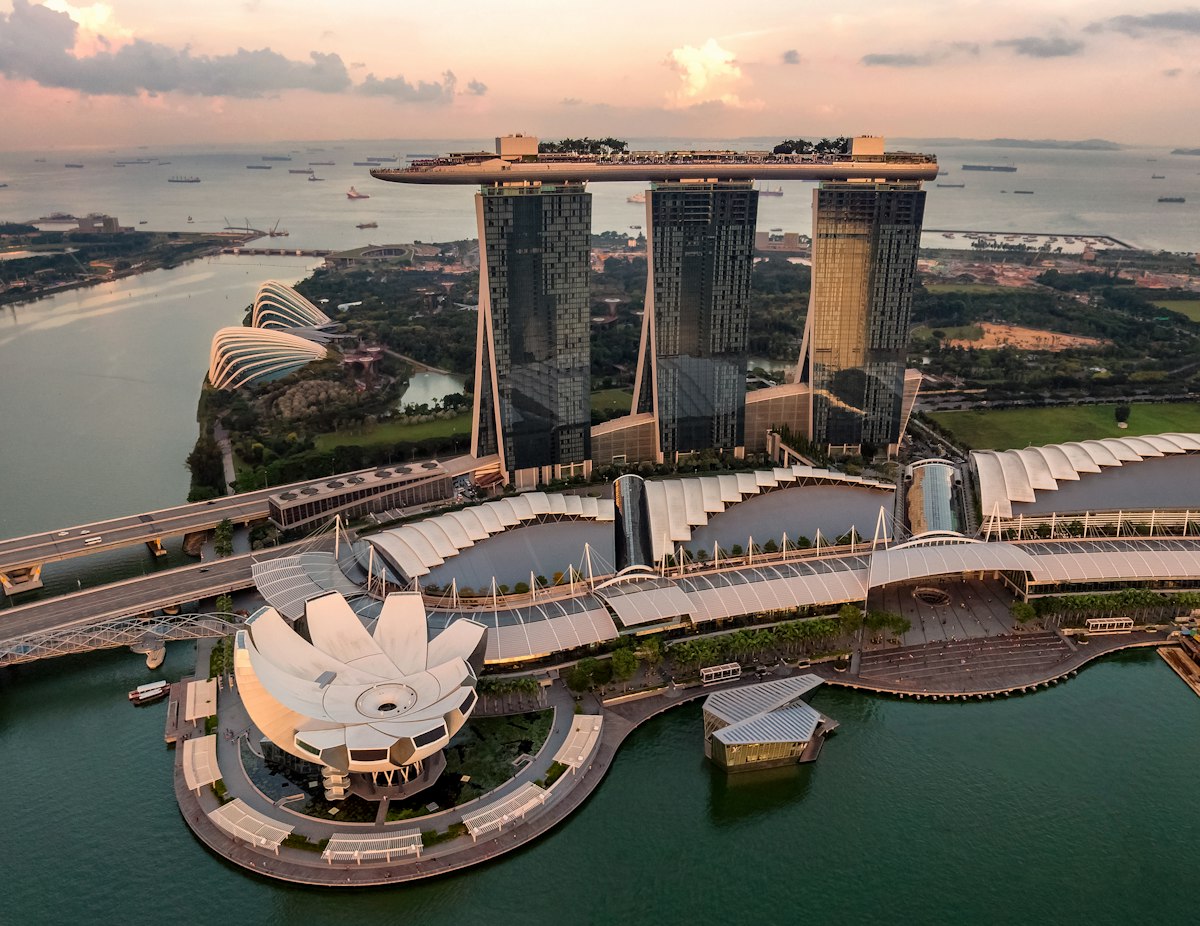
The Monetary Authority of Singapore opened a consultation on September 30 that would require prior approval for nominating committee chairs at locally incorporated banks and insurers, raise minimum board sizes and tighten the definition of an independent director.
Singapore's financial regulator wants a bigger say in who steers the boards of the country's banks and insurers. On September 30, 2026, the Monetary Authority of Singapore (MAS) opened a public consultation on changes to its Corporate Governance Regulations, which apply to banks, insurers and designated financial holding companies. Comments are open until December 9, 2026. The details below come from Insurance Business Asia's report on the consultation. We have not reviewed MAS's own consultation paper, and the report does not give the date on which any final rules would take effect, so readers should treat the proposals as drafts that may change.
The proposals cover four areas, according to the report: the criteria for judging whether a director is independent, the composition of boards, key appointments, and a lighter set of requirements for firms that are less important to the system. The most visible change for insurers is the nominating committee, the board committee that deals with who sits on the board, how directors are selected and how succession is planned. Under the proposal, the chairperson of the nominating committee at locally incorporated banks and insurers would be added to the roles that need MAS's prior approval before the person can take the job. At the moment, according to the report, the regulator already vets certain senior appointments, and this would extend that approval to the person who leads the process of choosing directors.
A second proposal concerns technology. MAS would require prior approval for the chief information officer of domestic systemically important banks. The report says this would not apply to the insurers designated as systemically important. A third change affects the size and make-up of boards: the minimum board size would increase, and domestic systemically important banks, insurers and full banks would need a majority of independent directors. The report does not state the current minimum or the new one, so we cannot say how many extra directors this implies.
The fourth proposal tightens what counts as independent. A director with an employment or commercial relationship with a related corporation or affiliate would be classed as non-independent, both from management and from business relationships. This matters for insurers that are part of larger groups, where a director might also sit on the board of a parent or sister company. MAS said, in the report's words, that 'Clear independence criteria support objective judgement and effective challenge.' The proposals would also apply the same governance standards to a designated financial holding company as to its bank or insurer subsidiary. On the other side, MAS proposes to drop prior approval for certain board and senior management appointments at firms with limited retail reach or lower systemic importance, which the regulator describes as streamlining.
Which insurers are affected? The report names the five insurers designated as domestic systemically important insurers, which face higher capital requirements and closer supervision: AIA Singapore, Income Insurance, Prudential Assurance Company Singapore, Great Eastern Life Assurance and Manulife Singapore. The consultation also covers other locally incorporated insurers, although the report does not list them. The report adds that MAS Notice 106, which governs insurer appointments, was last revised in May 2026, and that the new consultation would go further.
Why is the regulator doing this? MAS cited the growing importance of succession planning, technology and information risk management at board and senior management level. The report links the consultation to a wider theme in MAS's supervision. In a speech to the Life Insurance Association's annual luncheon on March 30, 2026, Assistant Managing Director Marcus Lim said that complaints 'should not be treated in isolation' and should be discussed at board and senior management levels. This indicates that the regulator expects boards to take direct ownership of customer outcomes, not leave them to operational teams. That is our reading of the speech as quoted in the report.
What does it mean for policyholders? In the short term, nothing changes: the consultation is a proposal and no new rules apply yet. Over time, stronger boards are intended to reduce the risk of poor governance, of weak technology controls and of conflicts of interest in groups. There is no guarantee that this will happen, and the report does not claim it. The report also frames the matter as a counterparty issue for brokers and large corporate buyers, suggesting that they check whether carriers meet the independence thresholds, how nominating committees are led and where technology risk accountability sits.
The next steps are for banks, insurers, industry bodies and the public to send comments by December 9, after which MAS will decide whether to adopt, amend or drop the proposals and will publish final rules with an effective date. Anyone affected should read the consultation paper itself on the MAS website. This article is a news summary, not legal or regulatory advice.
Key Points
- 1MAS opened a consultation on September 30, 2026 on changes to its Corporate Governance Regulations for banks, insurers and designated financial holding companies; submissions close on December 9, 2026.
- 2Nominating committee chairs at locally incorporated banks and insurers would need MAS's prior approval, and domestic systemically important banks would need approval for their chief information officer.
- 3Minimum board sizes would rise, and domestic systemically important banks, insurers and full banks would need a majority of independent directors.
- 4Directors with employment or commercial ties to related corporations or affiliates would be treated as non-independent, and lower-impact firms would be relieved of some prior-approval requirements.
- 5Five insurers are designated as domestically systemically important: AIA Singapore, Income Insurance, Prudential Assurance Company Singapore, Great Eastern Life Assurance and Manulife Singapore; the proposals do not yet have an effective date.
Why This Matters
Insurance policies are promises that may be paid decades from now, so how an insurer's board is chosen and held to account matters to policyholders. The proposals show where the regulator is looking: succession, technology risk and whether directors are truly independent of the group they oversee.
Related Stories
Japan's FSA Bars Prudential Life From New Sales Until January 31 After an Employee Fraud Scandal
October 17, 2026
SEBI Asks IRDAI to Add Insurance Data to the Consolidated Account Statement for a Single View of Investor Holdings
October 15, 2026
MAS Holds Its Singapore Dollar Policy Band Steady in October After Two Tightening Moves This Year
October 14, 2026
PRA Proposes Automatic Indexation of 128 Regulatory Thresholds to UK Nominal GDP, With the First Update in 2031
October 13, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer