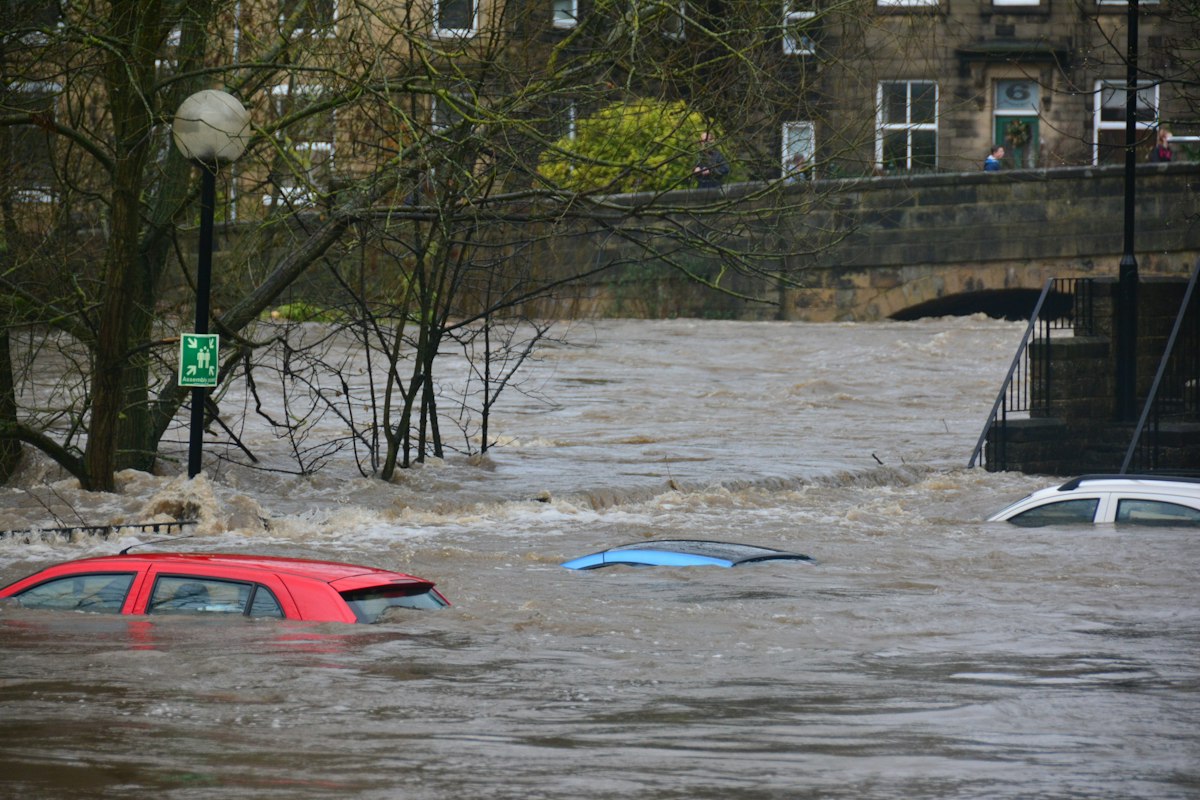
FEMA has opened direct online quotes and purchases of National Flood Insurance Program policies through FloodSmart.gov in nearly 22,700 communities, while the program's authorization runs out on December 12 and the agency's administrator says states must build their own reserves.
The Federal Emergency Management Agency has made it possible for homeowners to get a quote for and buy flood insurance online without an agent, according to reports from Insurance Business and Beinsure on October 21, 2026. The service runs through FloodSmart.gov, the public website of the National Flood Insurance Program, and is available in nearly 22,700 communities. The same reports say that a person who wants help can ask to be contacted by up to three local insurance agents, so the direct channel is described as an addition to the agent network, not a replacement for it.
To understand why this matters, it helps to know how flood insurance works in the United States. Standard homeowners policies generally exclude damage from rising water. Flood cover is bought separately, and most of it is sold through the NFIP, a federal program that offers policies to owners and renters in communities that adopt floodplain management rules. Many private insurers sell flood cover too, but the NFIP remains the largest provider. Historically, NFIP policies were sold mainly through insurance agents and through insurance companies that participate in the Write Your Own arrangement, and the policyholder often did not know that a separate flood policy was needed until a lender required one at the time of a home purchase or refinance. Letting people compare, price and buy online is intended to make that purchase easier for people who already know they want it.
The change arrives at a delicate moment for the program. The reports say the NFIP's authorization expires on December 12. According to the Congressional Research Service, as cited in the coverage, the program has been extended 37 times since fiscal year 2017, usually in short periods attached to other legislation. When authorization lapses, FEMA cannot sell new policies or renew existing ones. Claims on policies that were already in force continue to be paid in a lapse, but the interruption can delay real estate closings in areas where flood insurance is a condition of a mortgage. Each short extension postpones decisions on the structural issues that policy analysts have raised for years, such as the program's debt and the pricing of risk. Expiry on December 12 would, if no extension is passed, be the next test.
The coverage also reports a shift in tone from FEMA's leadership about who should carry disaster costs. Administrator Cameron Hamilton said states must build their own reserves. An internal memo dated October 15 reportedly aims to cut what it calls federal dependency. The reports present these as signals of direction rather than final policy, and the coverage does not set out the details of how the memo would be implemented or whether it applies to the flood insurance program itself. Another reference point is the FEMA Review Council, whose May 2026 recommendations are reported to include a centralized marketplace for flood insurance and an NFIP take-out program. A take-out program, in the NFIP context, generally means encouraging or moving policies from the federal program to private insurers; the reports do not give the details of the council's proposal, so its design remains unclear.
The exposure at stake is large and concentrated in specific places. The coverage gives the example of Hawaii, where there is more than $16.5 billion of NFIP coverage across more than 64,000 policies. An average of those figures would be roughly $250,000 of coverage per policy, which is simple arithmetic from the two reported numbers and is only an indication, because the distribution across homes, condominiums and commercial properties is not given. It does suggest that a relatively small number of policies can carry a large amount of insured value in coastal and island markets, which is why the continuity of the program matters for local property markets.
For consumers, the practical advice that follows from the reports is straightforward. Anyone who owns or rents in a community that participates in the NFIP can check availability on FloodSmart.gov, and anyone who prefers advice can ask for agent contact. Because flood policies usually take effect after a waiting period, commonly 30 days for many purchases though it varies, buying before a storm is forecast is what counts, and a lapse in authorization would make timing even more important for new buyers. The reports do not state the waiting period, so people should confirm it when they request a quote.
For the insurance industry, the direct channel raises questions about distribution. Agents have long been the main route to NFIP policies. The reports say the three-agent contact option remains, but the existence of a direct online route could change how customers shop, especially younger or more digitally oriented buyers who may prefer to self-serve. It could also change how private flood insurers market their products, since a federal website is now offering the instant purchase experience that online-first private carriers have promoted. How much business shifts is unknown, because the coverage includes no sales data.
What to watch is the December 12 deadline and whether Congress passes another short-term extension or a longer reauthorization; the response of states to the call to build reserves; and any follow-up from FEMA on how the October 15 memo and the Review Council recommendations will be put into practice. These decisions will shape the price and availability of flood protection for millions of households in the coming hurricane and storm seasons.
Key Points
- 1FEMA now lets homeowners get quotes for and buy National Flood Insurance Program policies directly on FloodSmart.gov without going through an agent, in nearly 22,700 participating communities.
- 2Customers can ask to be contacted by up to three local agents, so the new route sits alongside the traditional agent channel rather than replacing it.
- 3The NFIP's authorization expires on December 12; according to the Congressional Research Service it has been extended 37 times since fiscal year 2017, and policies cannot be sold or renewed while it lapses.
- 4FEMA Administrator Cameron Hamilton has said states must build their own reserves, and an October 15 internal memo reportedly seeks to reduce 'federal dependency'.
- 5Hawaii alone has more than $16.5 billion of NFIP coverage across more than 64,000 policies, and the FEMA Review Council's May 2026 recommendations included a centralized marketplace and an NFIP take-out program.
Why This Matters
The National Flood Insurance Program is the main source of flood cover for US homeowners because standard homeowners policies exclude flood. Selling directly online lowers one barrier to buying, but the program's recurring short-term authorizations and the administration's push for states to carry more of the risk raise a bigger question: who will pay for floods in the future. A lapse on December 12 would stop new and renewed policies, which can delay home purchases that require flood cover.
Original Source
Insurance Business (October 21, 2026), Beinsure (October 21, 2026) and Congressional Research Service ↗Related Stories

Allstate Reports $220 Million of September Catastrophe Losses, Taking Third-Quarter Losses to $1.65 Billion and Six-Month Losses to $3.4 Billion
October 26, 2026

Victoria Gazettes Mandatory Five-Tier Flood Risk Ratings, and Insurers Say the Planning Rules Could Reshape Premiums Where Homes Are Built
October 26, 2026

Canada's Cyber Insurance Market Stabilizes After the Ransomware Peak, but the Insurance Bureau of Canada Warns of Shared-Vendor and AI Concentration Risk
October 26, 2026
Moody's Keeps UK Life and Property Insurers at a Stable Outlook but Warns That Falling Prices Will Squeeze Underwriting Margins More Heavily in 2027
October 26, 2026
Daily Intelligence
The PolicyRix Daily Brief
Get the day's key insurance and finance stories in one email, each linked to its original source. No spam. Unsubscribe anytime.
Informational newsletter only. Not financial advice. Disclaimer